CAPITAL MARKETS · ASSET PRICING · RISK
The financial-economics questions that actually change a decision
Asset pricing, portfolio theory and capital structure only matter to Sheyconomics’ stakeholders when they change an entry price, a financing decision or a risk position. The rest is theory worth knowing but not worth pricing into a deal.
Where this matters, by seat
Investors
Whether an entry price actually compensates for the risk being taken, not just the return being advertised.
Boards & CFOs
How capital structure choices change the cost of capital and the room to maneuver in a downturn.
Portfolio managers
Where correlations quietly break down exactly when diversification is needed most.
FRAMEWORK
What to interrogate before pricing risk
Risk premium assumptions
Whether the assumed premium reflects current conditions or a prior cycle.
Correlation stability
Whether the assets diversifying a portfolio on paper actually move independently under stress.
Financing cost sensitivity
How much a plan depends on debt staying cheap, and what happens if it does not.
Behavioral blind spots
Where a team’s own biases, not the market’s, are driving the decision.
EXAMPLE
A portfolio company refinancing into a higher-rate environment
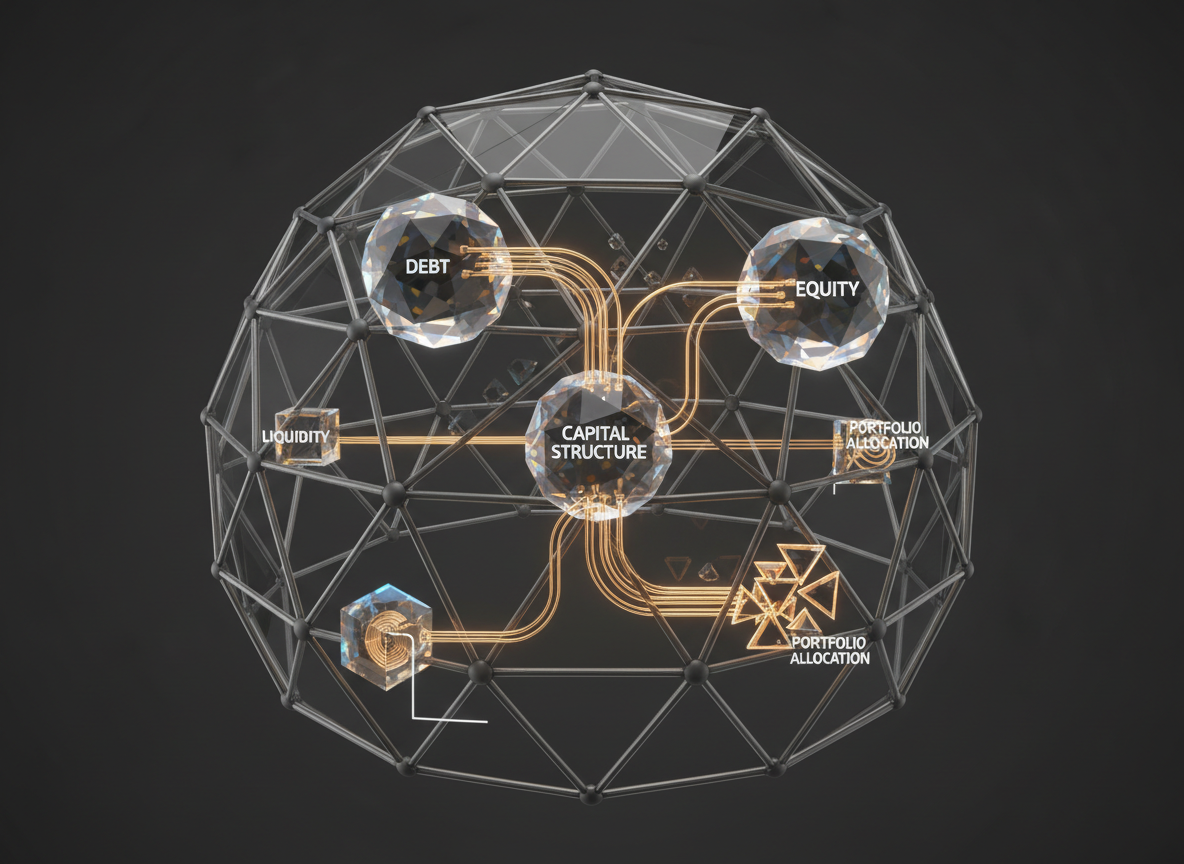
Context. A PE-backed company financed at a low fixed rate faced a refinancing wall as rates rose, with the sponsor assuming the same leverage multiple could simply be rolled over.
Analysis. Stress-testing the capital structure against realistic refinancing rates showed the existing leverage level would push interest coverage below covenant thresholds within two quarters of a full-rate rollover.
Output. The sponsor negotiated a partial paydown ahead of the refinancing and staggered the maturity, trading a smaller near-term equity check for materially lower covenant risk.
The bottom line
Most capital structure mistakes are not pricing errors, they are timing errors: assuming today’s financing conditions will still be there when the bill comes due. Stress-testing that assumption is cheap. Discovering it was wrong at the refinancing table is not.
The lesson. Price risk against the conditions likely to exist when the position actually needs to be exited or refinanced, not the conditions in place when it was put on.

